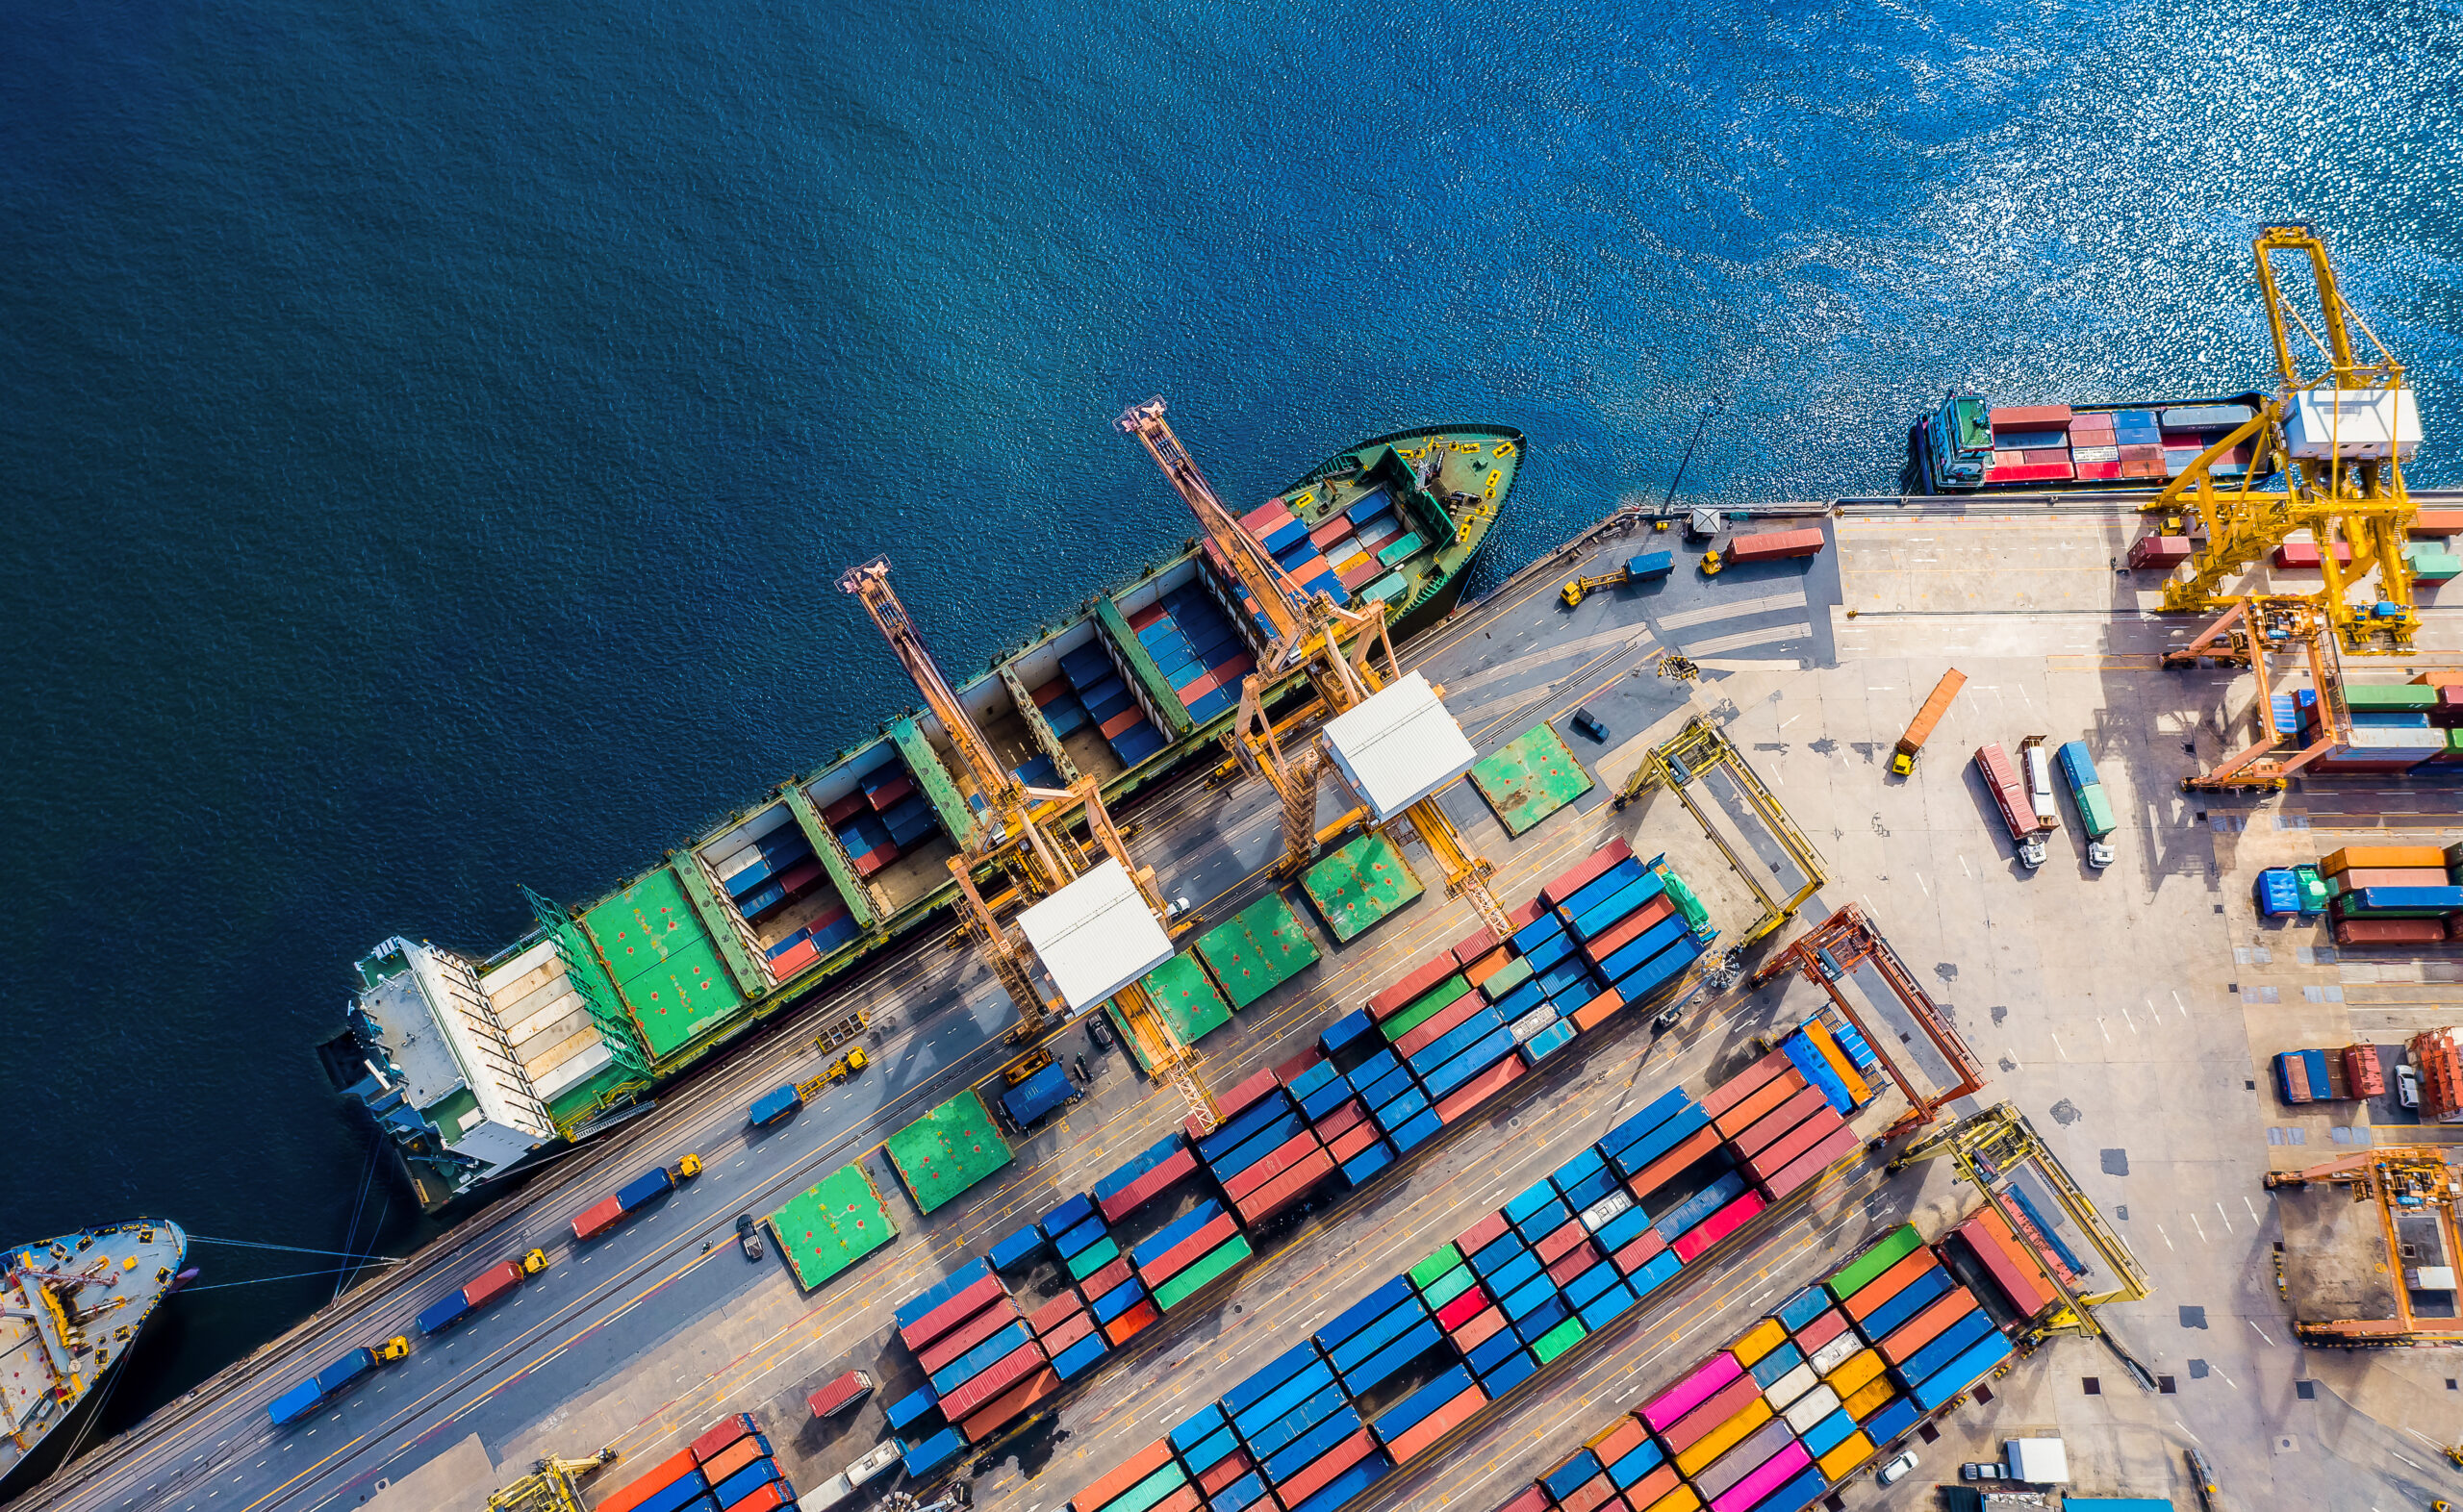
Ocean freight rates out of Asia have moved from commodity pricing to crisis pricing in under four months, and the increase will hit importer margins rather than dutiable value. Asia-to-US East Coast spot quotes above $11,000 per 40-foot container have quickly invalidated any cost models built on first-quarter baselines.
Key Takeaways
- Reprice landed cost per SKU at the current spot level, not the contract level, and identify which products are approaching negative.
- Confirm freight and insurance are separately stated on commercial invoices so they stay outside the dutiable value.
- Refresh UFLPA supplier traceability files now; detention costs scale with the freight market.
- Sequence bookings by margin contribution and shelf date rather than by order age.
Transpacific Rates Approach Pandemic Highs
Rate level and velocity. Asia-to-US East Coast spot pricing has cleared $11,000 per 40-foot container, with Asia-to-US West Coast nearing $8,000 per 40-foot container, roughly 320% above the late-February level and within reach of the 2021-22 congestion peaks [1]. Independent benchmarks including the Drewry World Container Index and Xeneta track the same direction of travel on the headline transpacific lanes [2][3].
What’s driving it. Capacity is being absorbed by longer routings, equipment is short at Asian load ports, and forward bookings are being pulled ahead of expected peak-season surcharges. Carriers can implement new or increased tariff rates on 30 days’ published notice under the FMC’s tariff publication rules, so the announced number and the collected number diverge quickly [4].
| Metric | Late February | Current | Change |
|---|---|---|---|
| Asia to USEC spot, per 40ft container | approx. $2,600 (implied) | above $11,000 | +320% |
| Illustrative cost per CBM at 65 CBM usable | approx. $40 | approx. $169 | +320% |
| Freight delta per 40ft container | baseline | approx. +$8,400 | n/a |
Landed Cost Math and Customs Valuation
Unit-level impact. An $8,400 freight delta spread across 20,000 units of small consumer electronics adds roughly $0.42 per unit. The same delta across 900 units of cube-heavy sporting goods or packaging adds more than $9 per unit, which is where gross margin will take the biggest hit.
Duty base stays flat. US appraisement is FOB-based, so international ocean freight and insurance are generally not dutiable when separately identified on the commercial invoice (19 CFR 152.103). Section 301 duties under 19 U.S.C. 2411 apply ad valorem to customs value on top of Column 1 rates, not to the freight bill [5][6].
Sector Exposure Across Priority Verticals
Low-value, high-cube cargo. Packaging, sporting goods, furniture-adjacent consumer goods, and entry-price apparel carry the worst freight-to-value ratio and will likely feel the impacts first. For these commodities, the freight line can rise from low single digits to double digits as a share of FOB cost.
Time-sensitive and regulated cargo. Automotive aftermarket parts, musical instruments, and consumer electronics face a different problem: replenishment timing tied to model-year or holiday sell-in. Paying for expedited service on a rising market is defensible for a launch SKU and indefensible for a safety-stock refill.
Compliance Exposure Rises With the Rate Curve
Entry summary timing. With container values inflated by freight rates, cash-flow planning around duty deposit matters more. The CBP Form 7501 entry summary and estimated duties are due within 10 working days of release, and late filing exposes the continuous bond to liquidated damages [5].
Forced labor detentions. A UFLPA detention now carries a far larger carrying cost than it did in February. The rebuttable presumption bars goods with a Xinjiang nexus under 19 U.S.C. 1307, and rebuttal requires transaction-level chain-of-custody records tracing finished goods back to raw material inputs [7].
Gateway and Capacity Watch
West Coast versus all-water. The cost gap that pushed importers to East and Gulf Coast gateways has narrowed, so the faster transit times out of Los Angeles and Long Beach are back in play. If you’re running lean on inventory, that speed difference matters. Los Angeles and Long Beach throughput data remains the cleanest public read on whether the surge is demand or pull-forward [8].
Equipment and reliability. Dedola’s booking desk is seeing tighter equipment availability at South China and Southeast Asian origins alongside weaker schedule adherence, which extends the effective order-to-shelf clock beyond the quoted transit [9].
Dedola has been helping importers navigate complexity and volatile freight rates for over 50 years, and we’re here to help. If you want help planning for your upcoming shipments, reach out to our team today.
References
- FreightWaves, “Ocean Rates and Surcharges” coverage, transpacific container spot rate reporting.
- Drewry Supply Chain Advisors, “World Container Index.”
- Xeneta, “Ocean Freight Rate Benchmarking and Market Analytics.”
- Federal Maritime Commission, “Demurrage and Detention Billing Requirements,” final rule, 46 CFR Part 541.
- US Customs and Border Protection, “Entry Summary (CBP Form 7501)” and 19 CFR Parts 142 and 152.
- Office of the United States Trade Representative, “Section 301 Four-Year Review: Notice of Modification.”
- Department of Homeland Security, “Uyghur Forced Labor Prevention Act” and CBP UFLPA Operational Guidance for Importers.
- Port of Los Angeles, “Container Statistics.”
- Sea-Intelligence, “Global Liner Performance: Schedule Reliability.”